
Let me ask you something real quick.
When your paycheck hits — do you have a plan for it, or does it just... disappear?
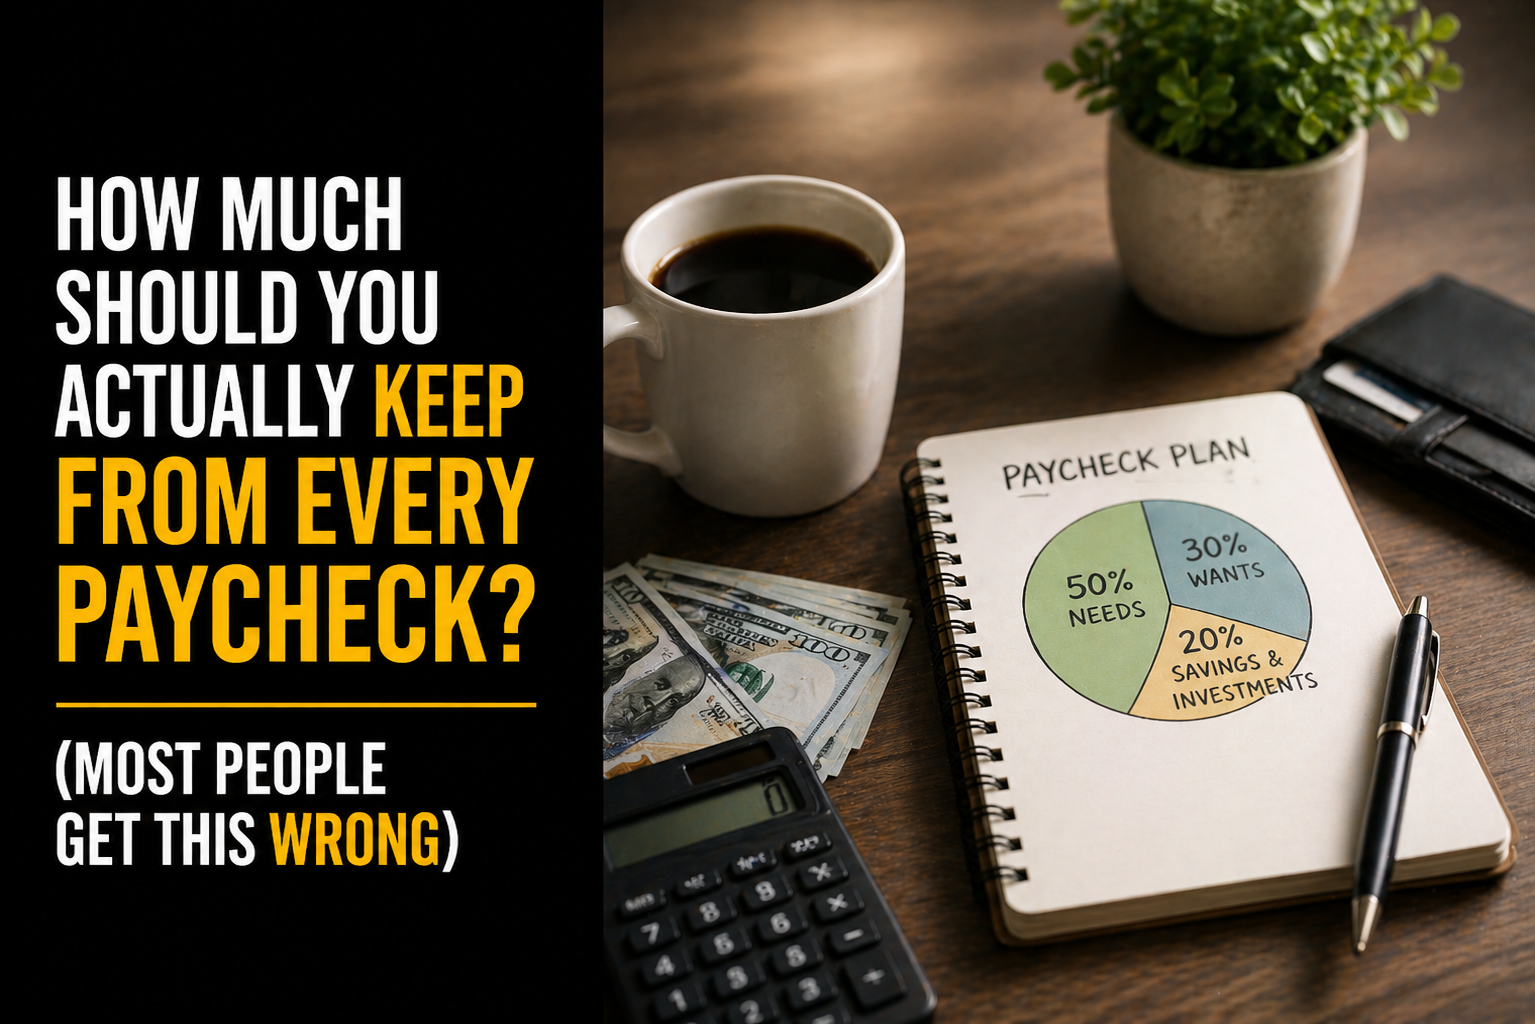
If you're being honest, most of us know that feeling. Money comes in, bills go out, and somehow there's nothing left to save. And then someone online tells you to "just save 20%" and you're sitting there thinking — 20% of what?
Here's what nobody's telling you: there is no magic percentage that works for everybody. The right amount to save depends entirely on where you are in your financial journey right now. Not where your coworker is. Not where your cousin is. Where you are.
Today I'm breaking it all the way down — simply, practically, and honestly. By the time you finish reading this, you'll know exactly how much you should be saving from every single paycheck.
Let's get into it.
Why the "Save 20%" Rule Isn't the Full Story
The 20% savings rule has been floating around for years. And look — it's not a bad goal. But it's an incomplete one.
Here's the problem: that rule doesn't account for debt.
If you're carrying $20,000 in student loans, $8,000 in credit card debt, and a car note — and someone tells you to save 20% of your paycheck — you're going to feel like you're failing every single month. Because the math won't work.
The truth is, you can't build wealth and drown in debt at the same time. Those two things are working against each other. Every dollar you're saving at 4% interest while paying 22% on a credit card is a losing trade.
So before we talk percentages, we need to talk about where you are — because that changes everything.
The Right Way to Think About Saving
Instead of chasing a percentage, I want you to think in stages. Your savings goal should match your current financial reality. Here's how I break it down.
Stage 1: Save $1,000 — Right Now, As Fast As You Can
If you don't have $1,000 sitting in a savings account, that is your only job right now.
Not $500. Not "a little something." One thousand dollars — and you need to get there as fast as humanly possible.
Why $1,000? Because life doesn't wait for you to be ready. A flat tire, an ER visit, a broken appliance — these things happen. And without a buffer, every emergency becomes a new debt. That cycle has to stop.
Most people can save $1,000 in 30 days if they get serious. Sell things you don't use. Pick up extra hours. Cut spending for a few weeks. Do what you have to do for a season.
Where to keep it: A basic savings account. Nothing fancy. Just somewhere safe that isn't your checking account.
Stage 2: Stop Saving and Destroy Your Debt
This is the stage that surprises people — but stay with me.
Once you have that $1,000 starter fund, you stop saving and redirect every extra dollar toward your debt. Every. Single. Dollar.
I know it feels backwards. But here's the reality: if you're paying 20–25% interest on debt while earning 4–5% in savings, you are losing money every month you wait. Debt is not neutral. It is actively working against your future.
The method that works — the only one I teach — is the debt snowball.
Here's how it works:
- List all your debts from smallest balance to largest
- Make minimum payments on everything except the smallest
- Throw every extra dollar at that smallest debt until it's gone
- Roll that payment into the next debt and repeat
It's not about math. It's about momentum. Every debt you eliminate is a win — and wins keep you moving.
This stage isn't about saving. It's about fighting for your freedom.
Stage 3: Build a Real Emergency Fund — 3 to 6 Months of Expenses
Once you're debt-free (outside of your mortgage), now you build real financial margin.
Three to six months of your basic living expenses — sitting in a high-yield savings account, ready if life gets hard.
This is what separates people who stay free from people who fall back into debt. A job loss, a medical bill, a family emergency — these things don't have to destroy you if you have margin built up.
Where to keep it: A high-yield savings account (HYSA). Let it earn interest while it waits. You're not trying to get rich off it — you just want it working while it sits.
Stage 4: Invest 15% of Your Income for Retirement
Now — and only now — do you start consistently investing for retirement.
The number is 15% of your gross household income. Not 5%. Not "whatever's left." Fifteen percent.
Why 15%? Because compound growth is one of the most powerful wealth-building tools available to everyday people — and the earlier you start, the harder it works for you.
Start with your employer's 401(k), especially if they offer a match. That match is free money. Don't leave it on the table.
Then look at a Roth IRA. Your money grows tax-free and comes out tax-free in retirement. For middle-class and working-class Americans, that is one of the best tools in the game.
The goal isn't just to retire. The goal is to retire with dignity, options, and something to leave behind.
Stage 5: Save for Your Children and Your Legacy
If you have kids, this is when you start building their college fund — after your retirement is in motion.
I know that might feel uncomfortable. But here's the truth: your kids have options. Scholarships. Grants. Work-study programs. Community college. You don't get a scholarship for retirement.
Secure your future first. Then build theirs.
And beyond college — this is the stage where you start thinking about generational wealth. Real estate. Investments. A paid-off home. Something your children's children's children can stand on.
How to Calculate Your Exact Savings Number Per Paycheck
Once you know your stage and your goal, the math is simple.
Your formula:
Savings Goal ÷ Months to Reach It ÷ Paychecks Per Month = Amount to Save Per Paycheck
Real example:
You want to save $6,000 for your full emergency fund in 6 months. You get paid twice a month.
- $6,000 ÷ 6 months = $1,000/month
- $1,000 ÷ 2 paychecks = $500 per paycheck
That's your number. Write it down. Put it in your budget. Treat it like a bill — because it is one. It's a bill you're paying to your future self.
5 Ways to Save More From Every Paycheck
Knowing your number is one thing. Finding the money is another. Here's how to make it happen.
1. Build a Budget — For Real This Time
You cannot save consistently without a budget. That's not an opinion — it's math.
A budget is not a punishment. It's a plan. It tells every dollar where to go before the month starts. Without it, money disappears and you're left wondering where it went.
Build a zero-based budget. Every dollar gets a job. Savings is a line item — not an afterthought.
2. Cut the Leaks
Go through your expenses line by line and be brutally honest.
How many subscriptions are quietly pulling from your account? How much are you spending on food you didn't cook? What are you paying for that you forgot you even signed up for?
Even cutting 150–200 a month frees up 1,800–2,400 a year. That's real money toward real goals.
3. Bring In More Income
Sometimes the budget is already lean and there's nothing left to cut. That's when you go earn more.
A side hustle. Extra hours at work. Selling things around the house. Offering a skill — lawn care, cleaning, tutoring, delivery driving.
One extra income stream — even temporarily — can completely change your savings timeline.
4. Automate Your Savings
Don't rely on willpower. Set up an automatic transfer to your savings account the same day your paycheck hits.
When the money moves before you see it, you stop missing it. Automation turns saving from a decision into a habit.
5. Adjust Your Tax Withholdings
If you're getting a large tax refund every year, that's your money — and you've been letting the government hold it interest-free all year long.
Adjust your withholdings so you keep more of your paycheck every month. Then put that extra directly toward your savings goal. Don't wait until April to get your own money back.
Where to Keep Your Savings
This matters more than most people think.
Starter Emergency Fund ($1,000)
Where to Keep It: Basic savings account
Full Emergency Fund (3–6 months)
Where to Keep It: High-yield savings account
Sinking Funds (car, vacation, gifts)
Where to Keep It: Separate savings account
Retirement (15%)
Where to Keep It: 401(k) + Roth IRA
Keep your savings separate from your checking account. Out of sight, out of reach. If it's easy to grab, you'll grab it.
Conclusion
Family, let me bring it home.
Saving money isn't about being perfect. It's about being intentional — every single paycheck, every single month.
Here's what we covered today:
- Forget the one-size-fits-all 20% rule — your number depends on your stage
- Start with $1,000 as fast as possible
- Attack your debt with the snowball method before you save big
- Build 3–6 months of expenses in a high-yield savings account
- Then invest 15% for retirement and build your legacy
You are not too far behind. You are not too broke to start. You are one decision away from a completely different financial story.
Here's your move right now: Figure out which stage you're in. Write down your savings goal. Break it down per paycheck using the formula above. And start this month — not when things slow down, not after the holidays, not next year. This month.
Which stage are you in right now? Drop it in the comments — I want to know where you're starting from so we can build together.
Keep building,

Lorem ipsum dolor sit amet, consectetur adipiscing elit. Suspendisse varius enim in eros elementum tristique. Duis cursus, mi quis viverra ornare, eros dolor interdum nulla, ut commodo diam libero vitae erat. Aenean faucibus nibh et justo cursus id rutrum lorem imperdiet. Nunc ut sem vitae risus tristique posuere.