
What if I told you that one desperate financial decision could cost you hundreds of thousands of dollars in retirement?
Not because you're bad with money. Not because you don't care about your future. But because nobody sat you down and told you the real price of cashing out your 401(k) early.
Family, I've been in tight spots. I know what it feels like when the bills are stacking up and you're staring at that retirement account thinking, "That money is just sitting there." But here's the truth — that money is not just sitting there. It's working for you. And the moment you pull it out early, you don't just lose what you take. You lose everything it was going to become.
Let's break this down together. No jargon. No fluff. Cookie jar on the bottom shelf — just real talk.
What Actually Happens When You Pull From Your 401(k) Early
Here's what most people don't realize: when you withdraw from your 401(k) before age 59½, the government hits you with a double penalty.
First, you pay income taxes on every dollar you take out — taxed at your regular rate. Then, on top of that, the IRS slaps you with a 10% early withdrawal penalty.
Let's make it real. Say you pull out $20,000 because you're in a tough spot. If you're in the 22% tax bracket, you're handing over $4,400 in income taxes plus another $2,000 in penalties. That's $6,400 gone — just like that. You walk away with $13,600 of your own $20,000.
But that's not even the worst part.
That $20,000, if left alone for 25 years at an average annual return of 11%, could have grown to over $300,000. You didn't just lose $6,400. You potentially gave up a quarter of a million dollars in future wealth.
That's not a small mistake, family. That's a generational one.
The Three Reasons You Should Never Do This
1. The Tax and Penalty Punch Will Knock You Out
I want you to really sit with this. You work hard for your money. You sacrifice. You budget. And then in one moment of financial panic, the government takes a third of it before you even get to use it.
That's not a deal. That's a trap.
2. You're Robbing Your Future Self
Your 401(k) is not a savings account. It's not a rainy day fund. It is a wealth-building machine that runs on two things — time and compound growth.
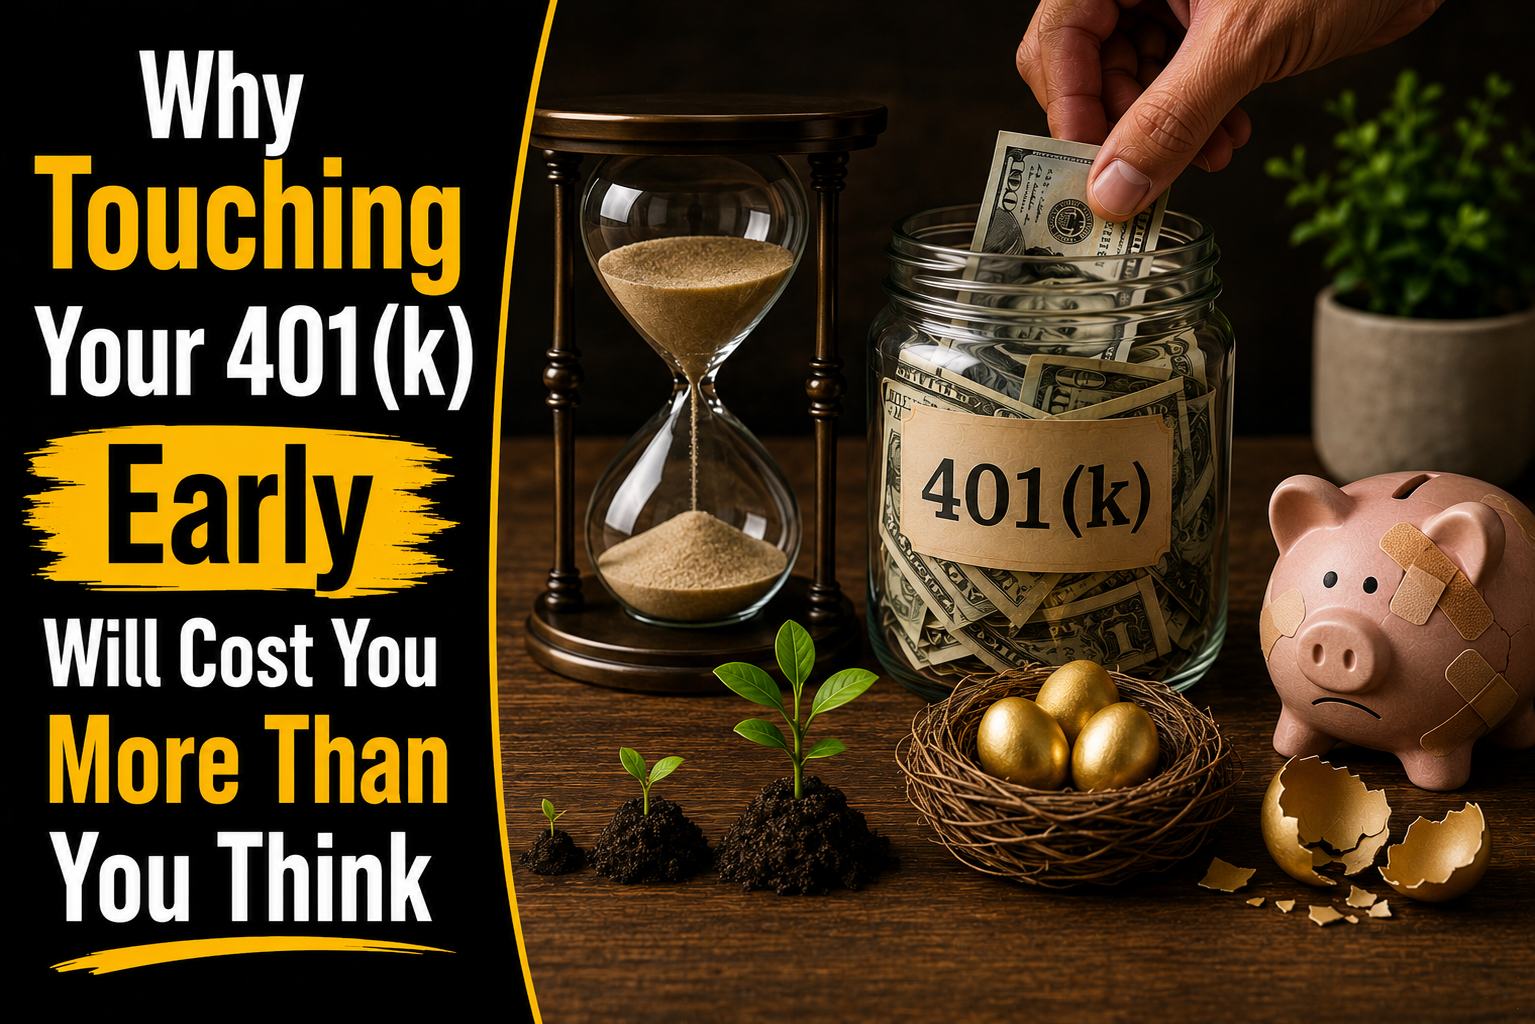
Think of it like a tree. You planted that seed years ago. Every contribution, every employer match, every year of growth — that's your tree getting taller. When you cash out early, you're not just cutting a branch. You're uprooting the whole thing and starting over with a seed.
Biblical wisdom teaches us to think generationally. Proverbs 13:22 says, "A good person leaves an inheritance for their children's children." You cannot leave a legacy if you keep raiding the foundation.
3. It Doesn't Actually Fix the Problem
Here's the hard truth — most people who cash out their 401(k) to pay off debt end up right back in debt within a few years. Why? Because the behavior didn't change. The system didn't change. Only the balance changed.
Cashing out your retirement is a Hail Mary when you don't need to throw one. It feels like relief, but it's really just delay.
What About a 401(k) Loan — Is That Any Better?
I get this question all the time. Family, a 401(k) loan is not the hero you think it is.
Yes, you avoid the 10% penalty. Yes, you're technically paying yourself back with interest. Sounds reasonable, right?
Here's what they don't tell you.
Your loan repayments are made with after-tax dollars. Then when you retire and withdraw that money, you pay taxes again. You are taxed twice on the same money. That is not a win.
And here's the part that should really make you pause — if you lose your job while you have an outstanding 401(k) loan, you typically have until the next tax filing deadline to pay the entire balance back. If you can't? The remaining balance is treated as an early withdrawal. Now you owe taxes and the 10% penalty on money you already spent.
You took on debt to yourself and still ended up in a worse position. That's not a strategy. That's a risk you don't need to take.
What About Hardship Withdrawals?
The IRS does allow something called a hardship withdrawal — a situation where you can pull from your 401(k) without the 10% penalty, though you still owe income taxes.
These are reserved for genuine emergencies:
- Unreimbursed medical expenses for you, your spouse, or dependents
- Costs related to buying your primary home
- Tuition and education fees for you or your family
- Payments to prevent eviction or foreclosure on your primary residence
- Burial or funeral expenses for a close family member
- Certain costs to repair damage to your primary home
Even if you qualify, I want you to hear me clearly — this should be your absolute last resort. You still lose the compound growth. You still pay income taxes. And you still set your retirement back.
Just because the door is open doesn't mean you should walk through it.
Better Options That Won't Cost You Your Future
Family, I know it feels like there's no way out when you're in a financial crisis. But I promise you — there are better moves than raiding your retirement.
Cut everything that isn't essential. Get on a written budget today. Cancel subscriptions. Pause the extras. Get lean for a season so you don't have to suffer for a lifetime.
Call your creditors and negotiate. Whether it's the IRS, a lender, or a medical provider — pick up the phone. Most creditors will work with you on a payment plan. You'd be surprised what a simple conversation can do.
Pick up extra income. A second job, freelance work, selling things around the house — it's temporary. Sacrifice for a season so you can build for a lifetime. Beans and rice for a season, family. That's the move.
Lean on your community. This isn't weakness. This is wisdom. Ask family if they can help with childcare, housing, or other expenses while you stabilize. We were never meant to do this alone.
Follow a proven plan. The debt snowball method works. Baby step by baby step, win by win — you build momentum and you build freedom. That's the system that changes lives.
What This Means For You Right Now
Here's the bottom line, family.
Your 401(k) is one of the most powerful tools you have for building generational wealth. It is not an emergency fund. It is not a credit card. It is your future — and your children's future — growing quietly in the background.
Every time you're tempted to touch it early, I want you to remember this: you're not just losing what you take out. You're losing everything it was going to become.
You are not too far behind. You are not too broke. You are one decision away from a new story. But that decision has to be the right one.
Protect your future. Leave that account alone. And if you're in a tough spot right now, reach out — there are resources, tools, and a whole community ready to help you find another way.
Conclusion
Look, family — this isn't about fear. It's about freedom.
We covered what early 401(k) withdrawals really cost you — the taxes, the penalties, the lost compound growth, and the generational impact of one desperate decision. We talked about why 401(k) loans aren't the safe alternative people think they are. And we walked through real, practical options that can help you get through a tough season without sacrificing your future.
You don't have to rob tomorrow to survive today.
Here's your move: If you're feeling the pressure right now, start with a written budget. Know exactly where every dollar is going. Then build your $1,000 starter emergency fund so the next crisis doesn't send you running to your retirement account.
You've got this. And I've got you.
Now I want to hear from you — have you ever been tempted to pull from your 401(k)? What stopped you, or what do you wish you had known? Drop it in the comments below. Let's build together.
Keep building,

Lorem ipsum dolor sit amet, consectetur adipiscing elit. Suspendisse varius enim in eros elementum tristique. Duis cursus, mi quis viverra ornare, eros dolor interdum nulla, ut commodo diam libero vitae erat. Aenean faucibus nibh et justo cursus id rutrum lorem imperdiet. Nunc ut sem vitae risus tristique posuere.