
Here's something most people don't know — and the credit card companies are perfectly fine keeping it that way.
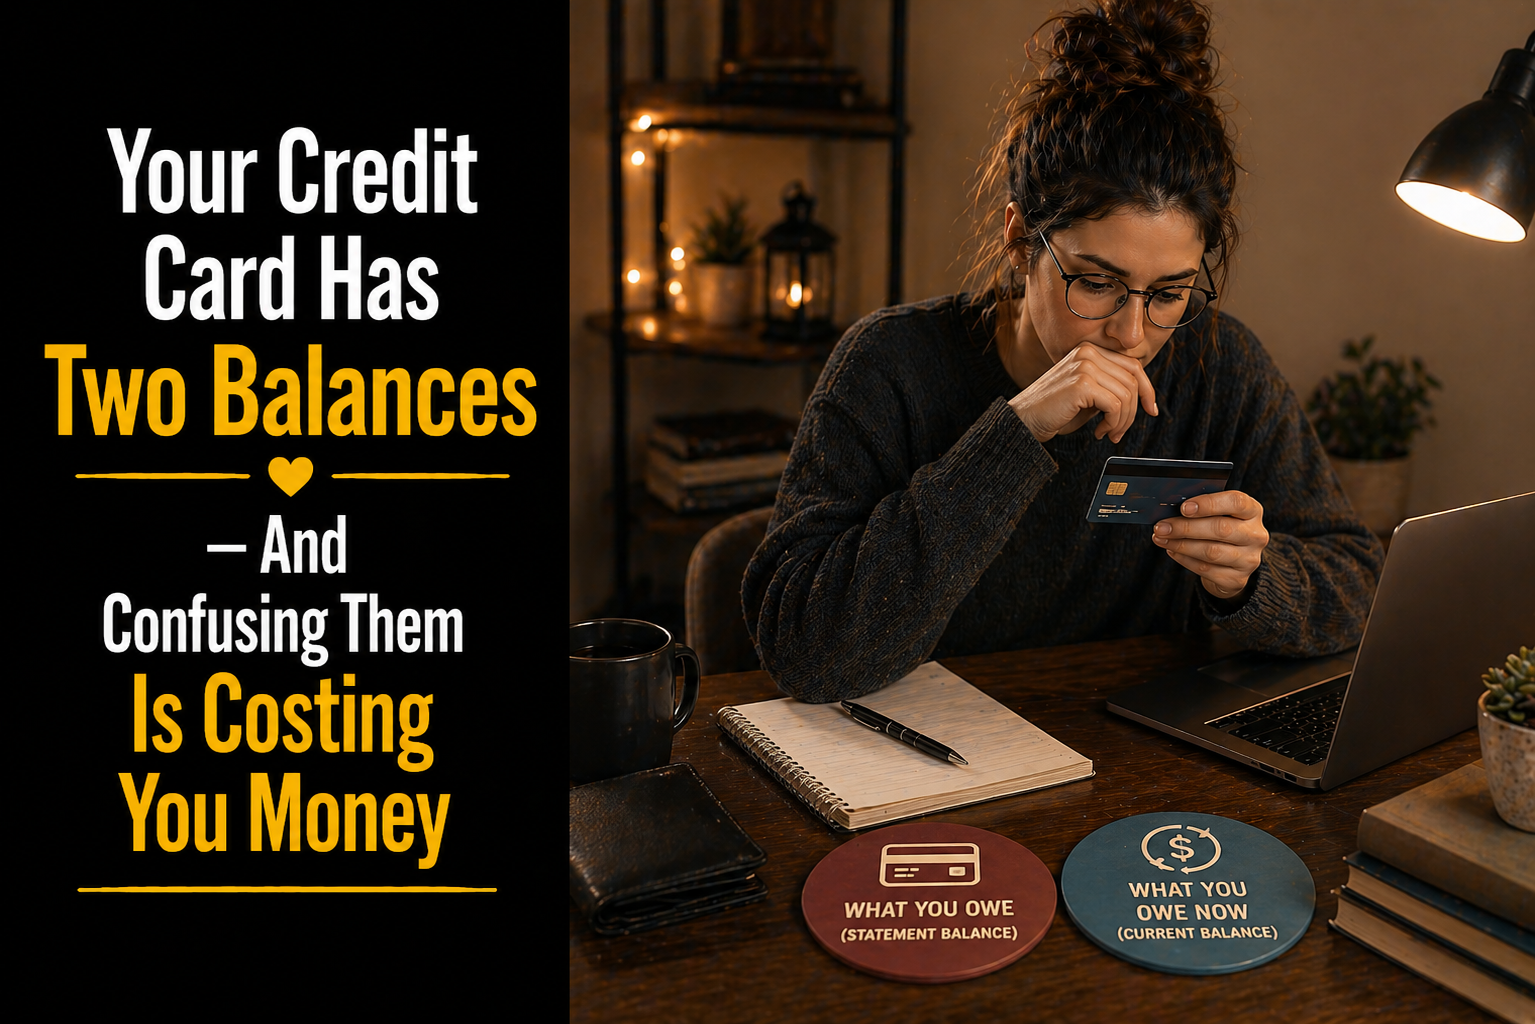
When you log into your credit card account, you'll usually see two different numbers staring back at you. One is your statement balance. The other is your current balance. They're not the same. And if you don't know the difference, you could be paying interest you never had to pay — or worse, falling deeper into debt without even realizing it.
Real talk: credit card companies make billions off confusion. The more complicated they make it, the more likely you are to slip up, carry a balance, and hand them your hard-earned money in interest and fees.
Today, I'm putting it on the bottom shelf — simple, clear, and actionable. Let's break this down so you never get caught off guard again.
Let's get to work.
What Is a Statement Balance?
Your statement balance is the total amount you owed on your credit card at the end of your last billing cycle.
Think of it like a snapshot. At the end of every billing period — usually every 28 to 31 days — your credit card company freezes the picture and says, "Here's what you owe." That frozen number is your statement balance.
It includes:
- Every purchase you made during that billing cycle
- Any interest charges or fees
- Any unpaid balance carried over from the previous month
You'll find this number on your monthly credit card statement — either in your email, your physical mail, or your online account. And here's the critical part: you must pay this amount by the due date or you'll be hit with late fees and interest on whatever's left.
The statement balance is the number that matters most when it comes to avoiding interest charges. Pay it in full, on time, every cycle — and you won't owe the credit card company a single dollar in interest.
What Is a Current Balance?
Your current balance is what you owe on your credit card right now — in real time.
Unlike the statement balance, which is locked in at the end of a billing cycle, your current balance is always moving. Every time you swipe your card, your current balance goes up. Every time you make a payment, it goes down.
Your current balance includes:
- Everything in your statement balance
- Any new purchases made after the billing cycle closed
- Any pending transactions
Here's something important to understand: your current balance is not the same as your available balance. Your current balance is what you owe. Your available balance is what you have left to spend — or more accurately, what you have left to borrow. Two very different things.
Why Are They Different?
This is where people get tripped up — and where credit card companies love to keep you confused.
Your statement balance is calculated once per billing cycle. But life doesn't stop when the billing cycle ends. You keep spending. You keep using the card. So by the time your statement balance is due, your current balance has already moved on.
Here's a real-life example:
Your October billing cycle runs from October 1–31. On November 1, your statement balance is locked in at $1,800. But it's now November 10, and you've already used your card to pay your phone bill, fill up your gas tank, and grab groceries. Your current balance is now $2,400 — even though your statement balance is still $1,800.
That gap between the two numbers? That's the new charges you've made since the billing cycle closed.
The credit card company isn't going to call you and explain this. They're hoping you stay confused, pay the minimum, and keep the interest rolling in.
Should You Pay the Statement Balance or the Current Balance?
Here's the straight answer, family:
Pay your statement balance in full by the due date — every single time.
That's the move that keeps you from being charged interest on your previous billing cycle's purchases. As long as you pay that full statement balance on time, you won't owe the credit card company a penny in interest for that period.
Now, if you want to go further and pay your current balance — meaning everything you owe right now, including new charges — that's even better. It brings your balance all the way to zero and reduces the risk of carrying anything into the next billing cycle.
Here's a simple breakdown:
Statement Balance
What it covers: Previous billing cycle charges
When to pay it: By the due date on your statement
Avoids interest? Yes, if paid in full on time
Best practice: Minimum requirement to avoid interest
Current Balance
What it covers: Everything you owe right now
When to pay it: Anytime — the sooner the better
Avoids interest? Yes, and reduces future risk
Best practice: The gold standard — pay this if you can
Will You Be Charged Interest If You Pay the Statement Balance?
No — if you pay your full statement balance by the due date, you will not be charged interest on those purchases.
That's the grace period working in your favor. Credit card companies are required by law to give you at least 21–25 days between the end of your billing cycle and your payment due date. Use that window. Pay in full. Walk away interest-free.
But here's the reality check: life happens. Emergencies come up. And the moment you can't pay that full statement balance, the credit card company starts charging you interest on the remaining amount — at an average rate of 23.37% APR. That's not a typo. Nearly a quarter of your remaining balance, added on top, every single year.
That's how a $1,800 balance quietly becomes a $2,200 balance before you even blink.
What If You Can't Pay the Full Statement Balance?
First — don't panic. But do take it seriously.
If you can't pay the full statement balance, pay at least the minimum payment due before the due date. This will:
- Keep you from being hit with late fees
- Protect your credit score from a negative mark
- Keep your account in good standing
What it will not do is protect you from interest. The moment you carry any balance past the due date, interest kicks in on what's left. And with rates averaging over 23%, that debt can grow faster than most people realize.
Here's the hard truth: if you're regularly unable to pay your full statement balance, the credit card isn't working for you — you're working for the credit card company.
Key Terms to Know
Let's make sure these stick, family. Here's your quick reference guide:
Statement Balance — What you owed at the end of your last billing cycle. Pay this in full by the due date to avoid interest.
Current Balance — What you owe right now, including new charges since the last billing cycle closed.
Minimum Payment Due — The smallest amount you can pay to avoid late fees. Paying only this will still result in interest charges on the remaining balance.
Available Balance — What you have left to spend (borrow) on your card. Not the same as what you owe.
Grace Period — The window between your billing cycle closing and your payment due date. Usually 21–25 days. Use it wisely.
APR (Annual Percentage Rate) — The interest rate charged on your unpaid balance. The national average is currently 23.37%. This is why carrying a balance is so dangerous.
How Your Balances Affect Your Credit Score
Here's something most people don't connect: your credit card balances directly impact your credit score — even if you're paying on time.
Credit card companies typically report your statement balance to the credit bureaus every month. That reported balance affects something called your credit utilization ratio — the percentage of your available credit that you're using.
The lower your utilization, the better your score. Most financial experts recommend keeping it under 30%. So even if you're paying your statement balance in full every month, a consistently high balance could still be dragging your score down.
The cleanest move? Pay early and often. Bringing your current balance down before the statement closes means a lower number gets reported to the bureaus — and that can give your score a real boost over time.
Conclusion
Look, family — I'm not going to tell you credit cards are the path to wealth. They're not. But if you're going to use one, you need to understand exactly how it works — because the house always wins when you're playing confused.
Here's what we covered today:
- Your statement balance is what you owed at the end of your last billing cycle — pay this in full by the due date to avoid interest
- Your current balance is what you owe right now, including new charges
- Always pay at least the minimum payment if you can't cover the full statement balance
- Carrying a balance at 23%+ APR is one of the fastest ways to fall deeper into debt
Here's your move: Log into your credit card account today. Find both numbers — your statement balance and your current balance. If they're higher than you're comfortable with, that's your sign to make a plan. Start with a budget, identify where the spending is coming from, and commit to paying that statement balance in full next cycle.
You don't have to stay confused. You don't have to stay stuck. One decision at a time, family.
Which of these terms did you not fully understand before today? Drop it in the comments — no judgment here. Let's learn together.
Keep building,

Lorem ipsum dolor sit amet, consectetur adipiscing elit. Suspendisse varius enim in eros elementum tristique. Duis cursus, mi quis viverra ornare, eros dolor interdum nulla, ut commodo diam libero vitae erat. Aenean faucibus nibh et justo cursus id rutrum lorem imperdiet. Nunc ut sem vitae risus tristique posuere.