

Key Takeaways
- Asset allocation is simply how you divide your investments across different types of assets — stocks, bonds, and cash.
- How you split up your portfolio will directly impact how much wealth you build over time.
- A growth-focused strategy — putting the majority of your money into growth stock mutual funds — gives you the best shot at outpacing inflation and building real wealth.
- Diversifying across four types of growth stock mutual funds adds an extra layer of protection while keeping your money working hard for your future.
There are moments in life that define your financial future. The day you decide to get out of debt. The day you open your first investment account. The day you stop letting fear make your money decisions for you.
But here's one that most people overlook — and it's costing them big: deciding how to divide up your investments.
Real talk, family. You can be doing everything right — contributing to your 401(k), investing consistently, staying out of debt — and still leave hundreds of thousands of dollars on the table because your money isn't divided the right way.
That's what asset allocation is all about. And today, I'm breaking it down in plain English so you can stop guessing and start building with intention.
Let's get to work.
So What Exactly Is Asset Allocation?
Asset allocation is just a fancy way of saying: how is your money divided across different types of investments?
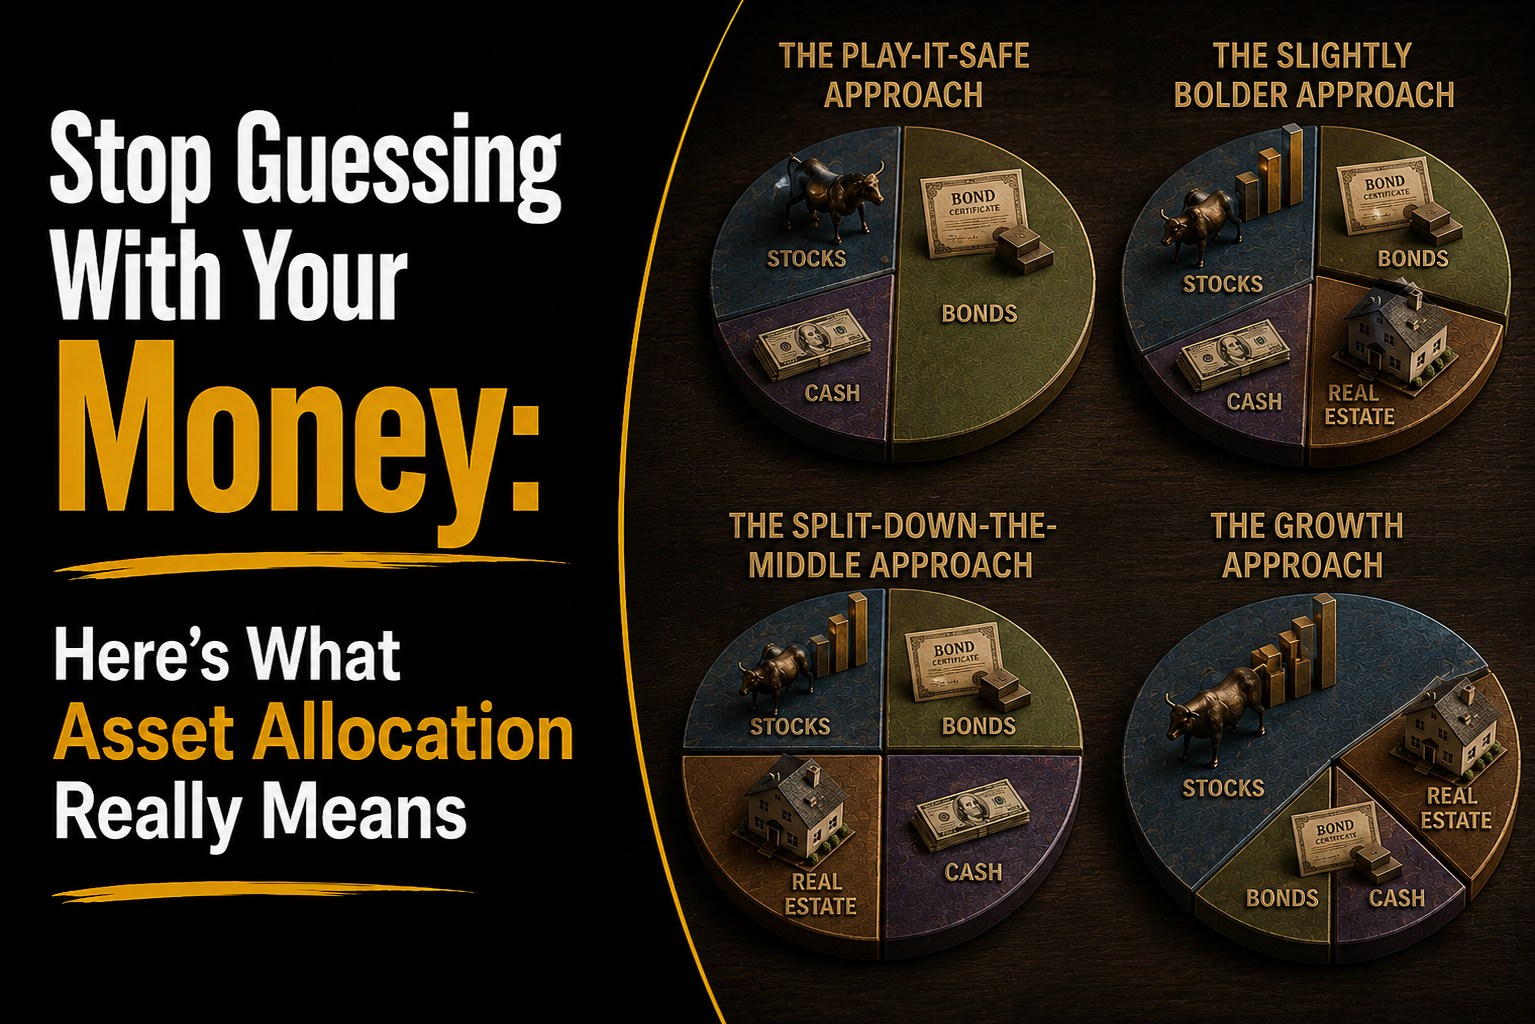
Think of it like a pie. Your investment portfolio is the whole pie, and asset allocation tells you how big each slice is. One slice might be stocks. Another might be bonds. Another might be cash or cash-equivalent investments.
For example, if you have 80% of your retirement portfolio in stocks, 15% in bonds, and 5% in cash — that's your asset allocation. Simple as that.
The reason this matters is because each type of investment carries a different level of risk and a different potential for return. Getting this balance right is one of the most important financial decisions you'll ever make.
Why This Decision Matters More Than You Think
Here's the truth nobody tells you at the kitchen table growing up: it's not just how much you invest — it's where you put it.
Two people can invest the same amount of money every single month for 30 years and end up with completely different results — all because of how their money was allocated.
If your money is sitting in low-return investments, inflation is quietly eating away at your purchasing power every single year. That means the money you worked hard to save is actually worth less over time.
On the flip side, when your money is properly allocated into growth-focused investments, you give it the best chance to grow, compound, and build the kind of legacy your children's children's children will benefit from.
This is not a small decision. This is a legacy decision.
The Four Ways People Divide Their Investments
Not all asset allocation strategies are created equal. Let me walk you through the four main approaches — and be honest with you about which ones actually work.
1. The Play-It-Safe Approach
This is for people who are so afraid of the market that they keep most of their money in bonds and cash. I understand the fear — I really do. But here's the problem: bonds average around 5% returns, and cash investments like CDs and money market accounts? Even less than that.
That's not going to build wealth, family. That's barely keeping up — and in many cases, it's falling behind inflation. Playing it too safe with your money is still a risk. It's just a slower one.
2. The Slightly Bolder Approach
This is where someone puts a little more into stocks — maybe a third — and keeps the rest in bonds and cash. It's a step in the right direction, but it's still not enough. The returns from bonds and cash simply don't have the power to grow your wealth the way you need over a 20 or 30-year period.
3. The Split-Down-the-Middle Approach
Half stocks, half bonds and cash. Sounds balanced, right? Here's the issue — stocks and bonds tend to move in opposite directions. When one goes up, the other often goes down. Splitting your portfolio evenly between the two is like trying to drive with one foot on the gas and one foot on the brake. You're not going to get very far.
4. The Growth Approach
This is the one I want you to pay attention to. A growth-focused allocation means the majority — or all — of your portfolio is in stocks, specifically growth stock mutual funds. Yes, the market will go up and down. But historically, the stock market has averaged between 10% and 12% annually over the long haul.
This is the approach that builds real wealth. Not overnight — but over time, with discipline and consistency.
The Smartest Way to Allocate for Growth
Now that you know growth is the goal, let me show you how to do it wisely.
The key is diversification — spreading your money across different types of growth stock mutual funds so you're not putting all your eggs in one basket.
Here are the four types of funds to spread your investments across:
Growth and Income Funds — These are your most stable, predictable funds. They invest in large, established companies that pay dividends. Lower risk, steady performance.
Growth Funds — These invest in companies that are growing steadily. A solid middle ground between stability and upside potential.
Aggressive Growth Funds — These are the high-risk, high-reward funds. They can swing big in either direction, but over time they have strong return potential. Don't put everything here — but don't ignore them either.
International Funds — These invest in companies outside the U.S. They add global diversification to your portfolio, which is a smart layer of protection.
Spreading your investments evenly across all four gives you growth potential and protection. That's the cookie jar on the bottom shelf version of smart investing — simple, accessible, and effective.
What This Means For You Right Now
Look, family — I know investing can feel overwhelming. Especially if nobody in your household ever talked about this stuff growing up. But here's what I need you to hear:
You don't have to be a Wall Street expert to build wealth. You just need a plan, the right strategy, and someone in your corner to help you execute it.
Asset allocation isn't about being perfect. It's about being intentional. It's about making sure every dollar you invest is working as hard as possible toward the future God designed for you.
You didn't come this far to leave money on the table. You came this far to build something that lasts.
Conclusion
Let's bring it home.
Asset allocation is simply how your investments are divided — and getting it right is one of the most important moves you can make for your financial future. We covered the four main approaches:
- The play-it-safe approach — too conservative, won't build wealth
- The slightly bolder approach — better, but still not enough
- The split-down-the-middle approach — sounds balanced, but works against itself
- The growth approach — this is the one that builds real, lasting wealth
The move? Invest in growth stock mutual funds, spread evenly across growth and income, growth, aggressive growth, and international funds. Keep it simple. Stay consistent. Think long-term.
Here's your next step: If you're not sure how your current investments are allocated, now is the time to find out. Connect with a trusted financial advisor who can walk you through your portfolio and make sure your money is working the right way for your future.
Now I want to hear from you — have you ever thought about how your investments are divided? Drop a comment below and let's talk about it.
Keep building,

Anthony O'Neal is a bestselling author, speaker and personal finance educator. He teaches families how to get out of debt and build real wealth on any income through The Escape Plan, his show The Table with AO, and the In the Black app.
more articles
Money Tips
November 2, 2026
Why Your Tax Refund Might Be Smaller Than It Should Be
Money Tips
November 2, 2026
The IRS Just Changed the Rules for 2026. Here's What It Means for Your Family.
Money Tips
November 1, 2026
Budgeting With Irregular Income: A System That Brings You Peace
Money Tips
November 1, 2026
Tell Your Money Where to Go: A Simple Guide to Zero-Based Budgeting
Money Tips
October 31, 2026
The Cash Envelope System: A Simple Way to Stop the Bleeding
Money Tips
October 31, 2026
What Should You Actually Be Spending on Groceries? A Breakdown by Family Size
Where this fits
The Escape Plan
Five phases, one plan. Find where you are, then take the next step.
In The Black
A coach in your pocket
Daily money assignments and real accountability, built around the Escape Plan. Know your next step every single day.
$59 a quarter or $179 a year
Get In The Black →Get the plan in your inbox.
Weekly money tips, real stories, and my free Wealth Checklist.
Free. Unsubscribe anytime.