
Key Takeaways
- Income is the money you earn. Net worth is the money you actually keep — and they are not the same thing.
- You can earn six figures and still have a negative net worth if debt is running your life.
- Net worth — not your salary — is the real measure of your financial health.
- Building wealth is not about how much you make. It is about what you do with what you have.
- Anyone, at any income level, can build a million-dollar net worth with the right plan and the right discipline.
Let me ask you something, family.
Have you ever gotten a raise — a real one — and somehow, a few months later, felt like you had even less money than before?
You are not imagining it. And you are not alone.
Millions of Americans are earning more than ever and still living paycheck to paycheck. Still stressed. Still one unexpected bill away from a crisis. And the reason most people never figure out why comes down to one thing they were never taught:
There is a difference between your income and your net worth — and confusing the two is costing you your future.
Today, we are going to fix that. I am going to break down exactly what income is, what net worth is, why they are not the same, and what you need to do right now to start building real wealth — not just a bigger paycheck.
Let's get to work.
What Is Net Worth — And Why Does It Matter?
Net worth is the number that actually tells the truth about where you stand financially.
Here is the simple formula:
What you own minus what you owe equals your net worth.
That is it. Add up everything you own — your savings, your retirement accounts, your home value, your car — then subtract every debt you carry. What is left is your net worth.
And here is where it gets real: that number can be negative. If you owe more than you own, your net worth is in the red. And no salary — no matter how impressive it looks on paper — can hide that.
What Does the Average American's Net Worth Look Like?
According to the U.S. Census Bureau, the median net worth of American households sits around $191,000. But that number shifts dramatically depending on age. Younger households are often just getting started, while those closer to retirement have had more time to build.
The point is not to compare yourself to a national average. The point is to know your number — because you cannot fix what you refuse to face.
What Counts as an Asset?
Assets are the things you own that hold value:
- Money in your checking or savings account
- Your retirement accounts — 401(k), Roth IRA, traditional IRA
- The current market value of your home
- The value of your vehicle
- Any investments or brokerage accounts
- Business equity, if applicable
What Counts as a Liability?
Liabilities are everything you owe:
- Your mortgage balance
- Car loans
- Student loan debt
- Credit card balances
- Medical debt
- Personal loans
Subtract the liabilities from the assets. That number — whatever it is — is your starting point. Not your ending point. Your starting point.
What Is Income — And What Is It Actually For?
Income is the money that flows into your life on a regular basis.
Your paycheck from your job. Profits from your business. Dividends from investments. Rental income. Side hustle money. All of it counts.
And here is something worth understanding: there are two versions of your income.
Gross income is what you earn before taxes and deductions come out. If your salary is $60,000 a year, that is your gross income.
Net income is what actually hits your bank account after taxes, Social Security, and any other deductions. That $60,000 salary might become $42,000 or $45,000 in take-home pay depending on your situation.
This distinction matters because a lot of people budget based on their gross income — and then wonder why they always come up short.
Here is the bottom line on income: your income is your most powerful wealth-building tool. But a tool only works when you use it correctly. A hammer sitting in a drawer builds nothing. And a paycheck that gets spent before it can be invested builds nothing either.
So What Is the Real Difference Between the Two?
Think of it this way.
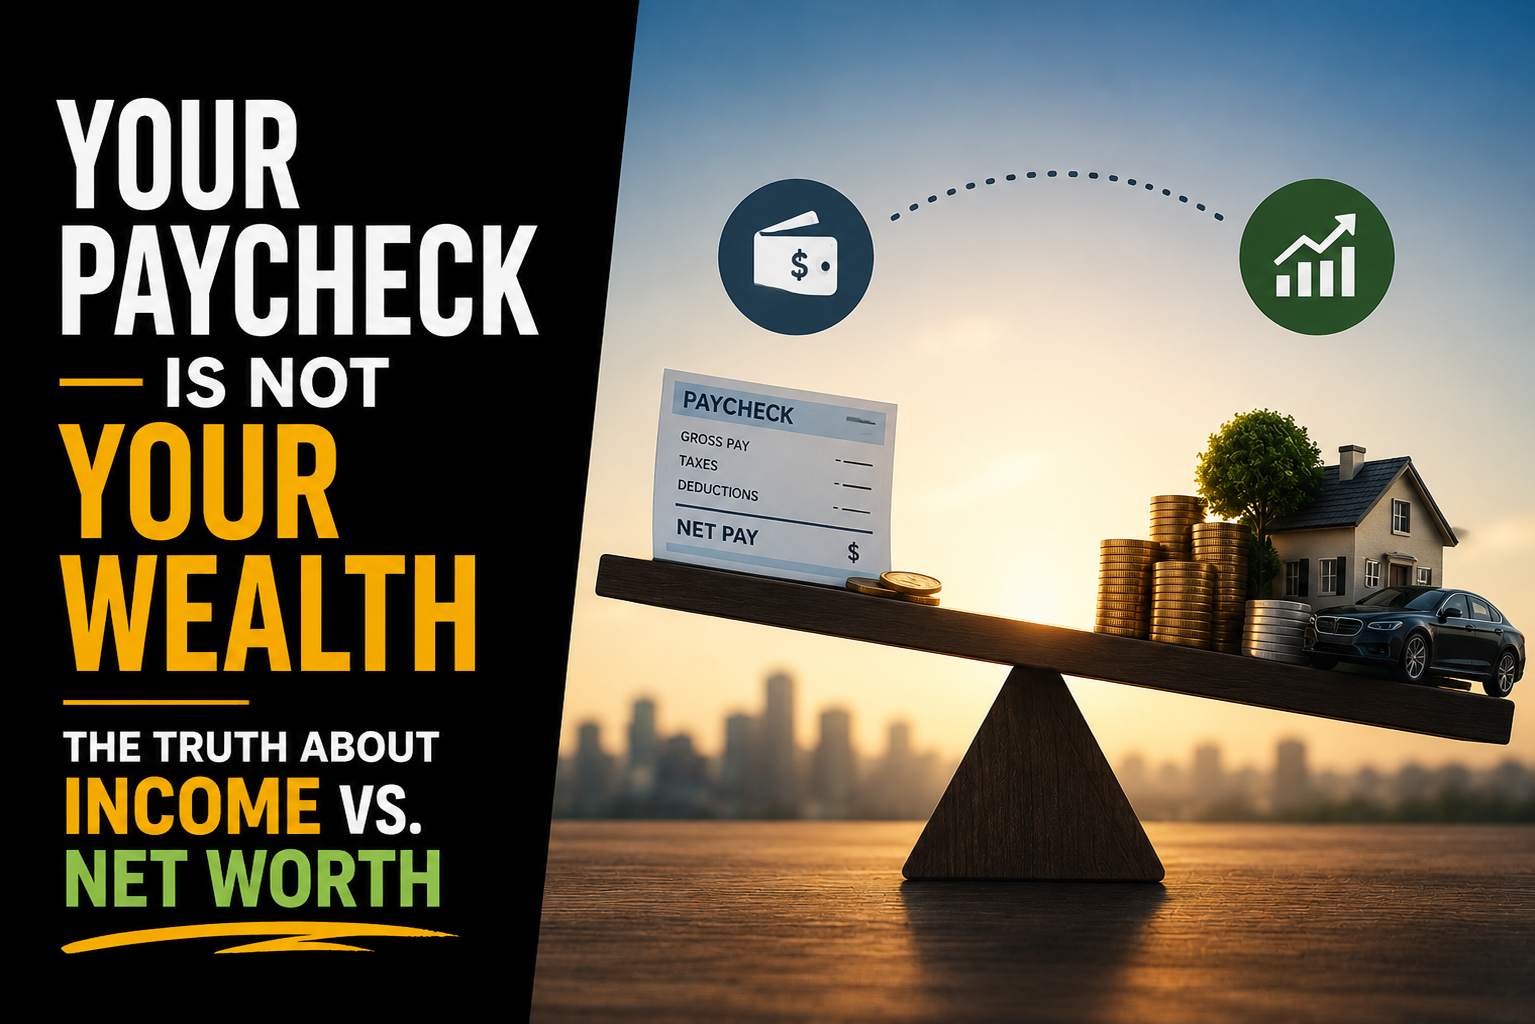
Your income is the water flowing into a bucket. Your net worth is how much water is actually in the bucket.
If the bucket has holes in it — debt, overspending, no savings plan — it does not matter how fast the water flows in. The bucket stays empty.
That is why you can find people earning $150,000 a year who are completely broke. And you can find people earning $45,000 a year who are quietly building real wealth. The difference is not the income. The difference is the holes in the bucket.
Income tells you how much is coming in. Net worth tells you how much is actually staying.
Is It Better to Have a Higher Income or a Higher Net Worth?
Let me give you a real-world picture of this.
Imagine two people. One is a corporate manager earning $140,000 a year. She has a luxury apartment, two car payments, student loans, and credit card debt she has been carrying for years. Her net worth? Barely $15,000.
The other is a school counselor earning $52,000 a year. She lives below her means, has been debt-free for three years, and has been consistently investing 15% of her income. Her net worth? Over $200,000 — and growing every month.
Who has more wealth?
The school counselor. By a long shot.
This is not a knock on high earners. A higher income absolutely gives you more tools to build with. But income without discipline is just a faster way to go broke. Real talk.
The research backs this up. Studies on millionaires consistently show that most of them never had massive salaries. They were teachers, engineers, and accountants who made steady, disciplined decisions over time. One-third of millionaires in America never earned a six-figure income in a single year.
Wealth is not about what you make. It is about what you keep, protect, and grow.
How to Start Improving Your Net Worth Today
This is where we stop talking and start moving. Here is the plan.
Step 1: Know Your Number
You cannot improve what you do not measure. Sit down this week and calculate your actual net worth. Write down every asset. Write down every debt. Get the real number on paper. No guessing. No avoiding. Just truth.
Step 2: Stop Giving Your Money Away
Every dollar you spend on things that do not move you forward is a dollar that cannot build your future. That does not mean you can never enjoy life — but it does mean you need a plan for every dollar before the month begins.
Build a budget. Give every dollar a name. When you tell your money where to go, it stops disappearing.
Step 3: Attack Your Debt With Everything You Have
Debt is the biggest threat to your net worth. Every balance you carry is a liability dragging your number down.
Use the debt snowball method. List your debts from smallest to largest. Pay minimums on everything, then throw every extra dollar at the smallest balance. When it is gone, roll that payment to the next one. Build momentum. Build wins. Keep going until the debt is gone.
Step 4: Build Your Emergency Fund
Once your debt is cleared, save three to six months of expenses in a fully funded emergency fund. This protects everything you are building. Without it, one hard season can undo years of progress.
Step 5: Invest 15% of Your Income Consistently
This is where your net worth starts to grow in a serious way. Start with your employer's 401(k) — especially if there is a match. That match is free money. Then open a Roth IRA and let compound interest do the work over time.
Here is what the math looks like: if you invest 15% of a $60,000 salary at an average annual return of 10 to 11% over 30 years, you could be sitting on over $1.7 million at retirement. Not because you earned a massive income. Because you were consistent.
Step 6: Pay Off Your Home and Build Legacy
Pay off your mortgage early. When your home shifts from a liability to a fully owned asset, your net worth jumps significantly. Then you build — for your children, your community, and generations you may never meet.
Your children's children's children should feel the decisions you make today.
When Do You Actually Become a Millionaire?
Here is something that might shift your thinking.
You become a millionaire when your net worth — not your annual income — reaches one million dollars.
That means if you have $650,000 in retirement accounts, a paid-off home worth $350,000, and zero debt, you are a millionaire. It does not matter what your salary is. It matters what you own versus what you owe.
And this is more achievable than most people believe. The path is not complicated. It is just not easy. It requires discipline, consistency, and a willingness to delay gratification for a season so you can enjoy freedom for a lifetime.
Beans and rice for a season. Then you enjoy life — debt-free, on your terms.
Conclusion
Family, let me bring it home.
Your income is not your wealth. Your salary is not your security. And your paycheck is not proof that you are winning financially.
Here is what we covered today:
- Net worth is what you own minus what you owe — and it is the real measure of your financial health
- Income is your most powerful wealth-building tool, but only when you use it with discipline
- Debt is the biggest threat to your net worth — and the debt snowball is the proven way to eliminate it
- Consistent investing over time — not a massive salary — is what builds millionaires
- Anyone, at any income level, can build real wealth with the right plan
Here is your move: This week, calculate your net worth. Get the real number. Then decide — is this the story you want to keep telling, or is it time to write a new one?
You are not too far behind. You are not too broke. You are one decision away from a different future.
Now I want to hear from you — did your net worth number surprise you? Drop it in the comments below. Let's talk about it and build together.
Keep building,

Anthony O'Neal is a bestselling author, speaker and personal finance educator. He teaches families how to get out of debt and build real wealth on any income through The Escape Plan, his show The Table with AO, and the In the Black app.
more articles
Money Tips
October 14, 2026
Stop Buying Dad Stuff. Give Him This Instead.
Money Tips
October 14, 2026
Still Living Paycheck to Paycheck? Here's the Budget App Difference Nobody Explains
Money Tips
October 13, 2026
The Real Timeline: What It Actually Takes to Become Debt-Free
Money Tips
October 13, 2026
Your Guide to Debt Payoff Apps: What They Do, What They Don't, and How to Choose One
Money Tips
October 12, 2026
The Quiet Cost of Ignoring a Credit Card Bill
Money Tips
October 12, 2026
Is Your Credit Card Balance a Warning Sign? Here's the Truth Nobody Tells You
Where this fits
The Escape Plan
Five phases, one plan. Find where you are, then take the next step.
In the Black
A coach in your pocket
Daily money assignments and real accountability, built around the Escape Plan. Know your next step every single day.
$19.00 a month
Get In the Black →Get the plan in your inbox.
Weekly money tips, real stories, and my free Wealth Checklist.
Free. Unsubscribe anytime.