
Let me give you a number that should stop you in your tracks.
$1.6 trillion.
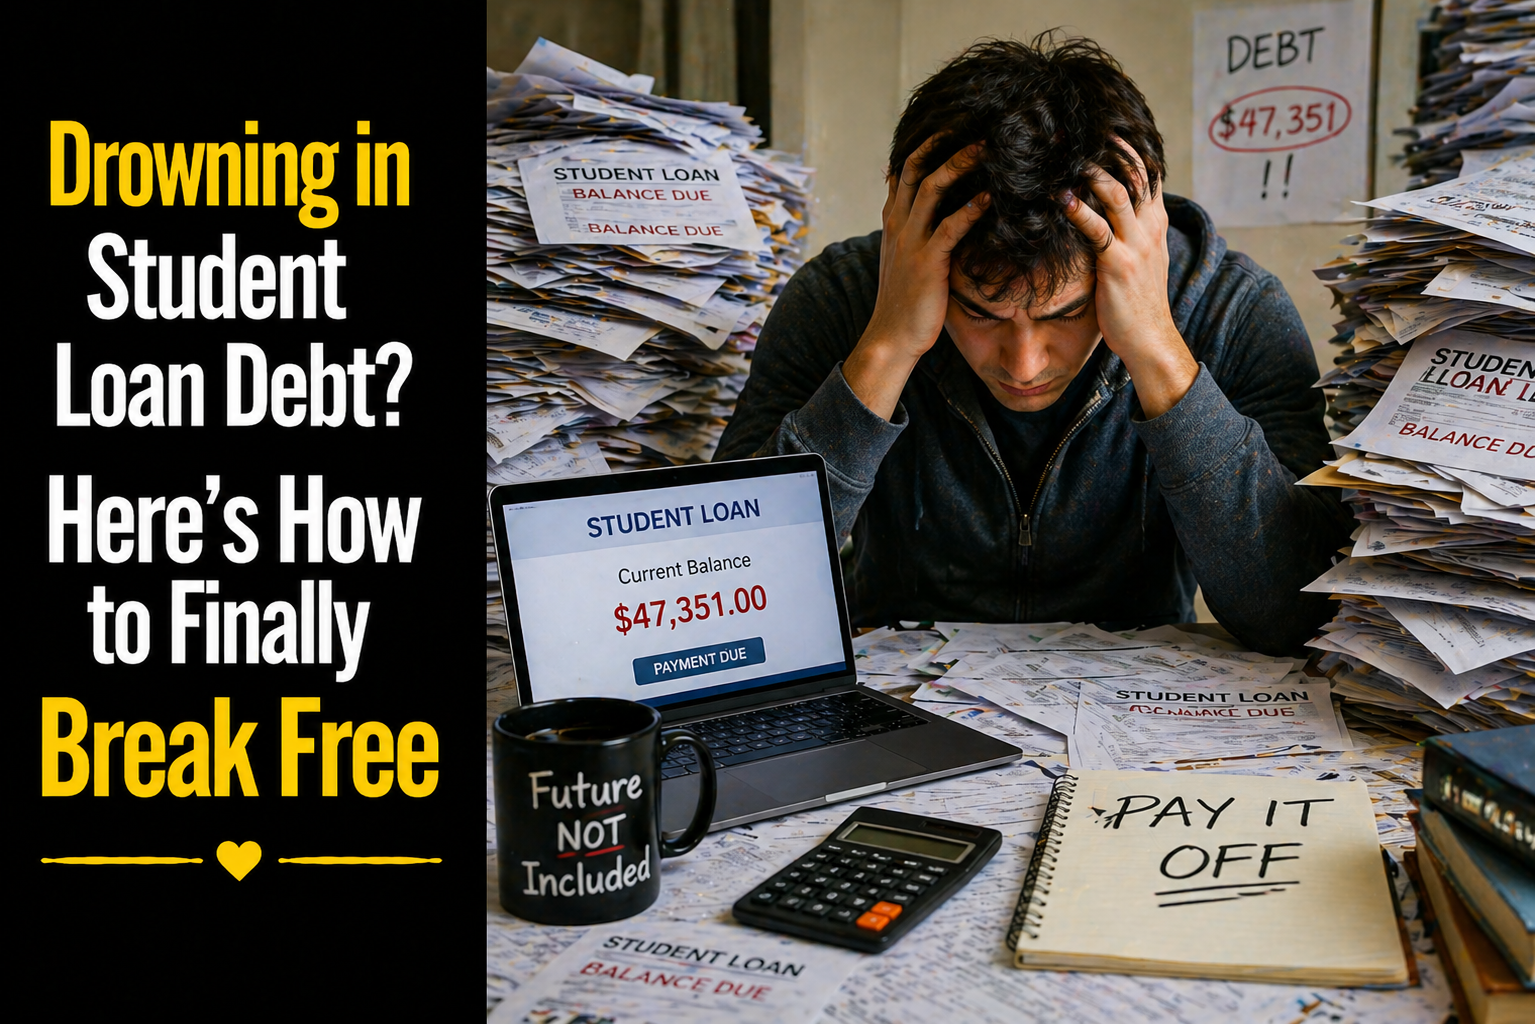
That's how much Americans owe in student loan debt right now. Not credit card debt. Not car loans. Student loans — the debt we were told was "good debt." The debt we were told was an investment in our future.
Family, I need you to hear me on this: there is no such thing as good debt. And $1.6 trillion in proof is sitting right in front of us.
The student loan crisis is real. It is heavy. And for too many people — especially in our community — it is quietly stealing the future you worked so hard to build.
But here's the truth: you don't have to stay stuck. Today, I'm breaking down exactly what's happening, why it happened, and the practical steps you can take to start climbing out — for good.
Let's get to work.
The Numbers Behind the Crisis
Before we talk solutions, let's look at the reality. Because you can't fix what you don't fully understand.
Total U.S. Student Loan Debt
$1.6 trillion
Total Growth in Student Debt Since 2020
$60+ billion
Number of Borrowers in the U.S.
43 million
Percentage of 2023 Grads Who Used Loans
59%
Average Debt per Borrower
$38,000
Average Monthly Payment
$500
Average Years to Pay Off Student Loans
20 years
Read that last line again. Twenty years.
That means someone who graduated at 22 could still be making student loan payments at 42. While trying to buy a house. While trying to raise kids. While trying to save for retirement. All at the same time.
That's not an investment. That's a trap.
How Did We Get Here?
Student loans didn't always exist. They started back in 1957 — originally designed to push more Americans into science and math fields during the space race with Russia. And it worked. College attendance shot up.
But so did the cost.
Tuition today is nearly 20 times higher than it was 50 years ago. And instead of addressing that problem, the system handed students a credit card with a diploma attached and called it opportunity.
Here's what actually happened:
- Society told us a degree was the only path to success
- Schools raised tuition because loans made it easy to pay
- Students borrowed more than they understood
- Graduates entered the workforce with debt that outpaced their starting salaries
- And 43 million people are now living with the consequences
This wasn't an accident. It was a system. And understanding that system is the first step to beating it.
Who Is Actually Carrying This Debt?
Here's something most people don't realize — student loan debt isn't just a young person's problem. It follows people for decades.
Ages 18–29
Total Student Loan Debt Carried: $320 billion
Ages 30–39
Total Student Loan Debt Carried: $520 billion
Ages 40–49
Total Student Loan Debt Carried: $360 billion
Ages 50–59
Total Student Loan Debt Carried: $240 billion
Ages 60–69
Total Student Loan Debt Carried: $120 billion
The 30–39 age group carries the most student loan debt of any age group in America. These are people who should be buying homes, building retirement accounts, and creating generational wealth — instead, they're still paying for a degree they got over a decade ago.
And for our community specifically, the weight is even heavier. Black borrowers carry more debt on average and take longer to pay it off — because the racial wage gap doesn't disappear with a diploma.
The Real Cost Nobody Warned You About
Let's do the math on what $38,000 in student loans actually costs you.
At a 6.53% interest rate with a $500 monthly payment — you'll be paying that loan for nine years. And by the time it's gone, you won't have paid $38,000.
You'll have paid nearly $49,000.
That extra $11,000 went straight to interest. That's $11,000 that could have been an emergency fund. A down payment. An investment account. A head start for your kids.
But the financial cost isn't even the whole story. Here's what student loan debt is doing to people's lives:
- 42% are delaying paying off other debt
- 38% are delaying saving for retirement
- 35% are delaying travel
- 33% are delaying buying a home
- 16% are delaying having children
- 14% are delaying getting married
Debt doesn't just steal your money. It steals your milestones. It steals your margin. It steals your peace.
And that is not the life God designed for you.
The Lie That Kept Us Borrowing
Real talk — we have to address the mindset that got us here.
We were told that a college degree was the only ticket to a good life. And so millions of people — many of them first-generation college students, many of them from our community — signed loan documents they didn't fully understand, for degrees they weren't sure about, at schools they chose based on prestige instead of price.
Here's what nobody told us:
- A degree from a community college is still a degree
- Trade skills can earn six figures without a single student loan
- The school name on your diploma matters far less than what you do after graduation
- You can get a great education and graduate debt-free — if you plan for it
Now, I'm not telling you not to go to college. Some fields require it. Education is valuable. But the cost of that education matters. And no one should take on $80,000 in debt for a degree that pays $35,000 a year. That math will never work.
How to Start Getting Out — Right Now
If you're already carrying student loan debt, I need you to hear this clearly:
You are not too far gone. This is fixable.
Here's your game plan:
Step 1: Face the full number.
Log into studentaid.gov for federal loans and contact your private servicer for any private loans. Write down every balance, every interest rate, every monthly payment. You cannot fight what you refuse to look at.
Step 2: Build a written budget.
Every dollar needs a job before the month begins. A budget isn't a punishment — it's a plan. And when you have a plan, you find money you didn't know you had. That money goes straight to your debt.
Step 3: Attack it with the debt snowball.
List your loans from smallest balance to largest. Throw everything extra at the smallest one while making minimum payments on the rest. When it's gone, roll that payment into the next loan. One win builds momentum for the next.
Step 4: Cut spending — for a season.
Beans and rice for a season, family. Not forever. But right now, every dollar you're not spending is a dollar working toward your freedom. Cancel subscriptions. Cook at home. Delay the vacation. The sacrifice is temporary. The freedom is permanent.
Step 5: Increase your income.
A side hustle, overtime, selling things around the house — every extra dollar speeds up your timeline. You don't have to live like this for 20 years. With intensity and focus, people pay off debt in 2–3 years. It's possible.
Step 6: Explore your options — carefully.
Public Service Loan Forgiveness is real for those who qualify. Income-driven repayment plans can provide short-term relief. But be careful — there are predatory companies out there promising forgiveness they can't deliver. Do your research. Protect yourself.
Protecting the Next Generation
Here's the part that matters most to me.
We can get ourselves out of this. But our job doesn't stop there. We have a responsibility to make sure our kids and grandkids never have to carry this weight.
That means:
- Talking about money early. Don't wait until they're 17 and filling out FAFSA to have the money conversation.
- Teaching them to apply for scholarships aggressively. Free money exists. Help them find it.
- Showing them all their options. Community college, trade school, work-study, ROTC — there are paths to education that don't require decades of debt.
- Being honest about what you can and can't afford. That conversation is hard. But it's a lot easier than watching your child graduate into a financial crisis.
Your children's children's children are counting on the decisions you make today. That's not pressure — that's purpose.
Conclusion
Family, let's bring it home.
Here's what we covered today:
- Americans owe over $1.6 trillion in student loan debt across 43 million borrowers
- The average borrower carries $38,000 in debt and takes 20 years to pay it off
- Student loans are delaying homeownership, retirement, marriage, and family for millions
- The "college at any cost" mindset is a trap — and there are real alternatives
- You can get free using a budget, the debt snowball, increased income, and focused intensity
You didn't create this crisis. But you have the power to end it — in your own life, and in your family's story.
The student loan system was designed to keep you paying. You were designed for something greater.
Here's your move: Grab the free debt calculator at anthonyoneal.com. See exactly where you stand. Then come back and let's build a plan together.
Now I want to hear from you — has student loan debt delayed something important in your life? Drop it in the comments below. Let's talk about it, and let's build together.
Keep building,

Lorem ipsum dolor sit amet, consectetur adipiscing elit. Suspendisse varius enim in eros elementum tristique. Duis cursus, mi quis viverra ornare, eros dolor interdum nulla, ut commodo diam libero vitae erat. Aenean faucibus nibh et justo cursus id rutrum lorem imperdiet. Nunc ut sem vitae risus tristique posuere.