
Let me ask you something, family.
What if I told you that one of the most popular "wealth-building strategies" being sold in barbershops, church lobbies, and financial seminars is actually one of the biggest money traps you can fall into?
That's exactly what's happening with whole life insurance being sold as an investment.
Every day, hardworking people — especially in our community — are being pitched permanent life insurance policies as a way to build wealth, leave a legacy, and grow tax-free money. It sounds good. It feels responsible. And the person selling it to you looks like they genuinely care.
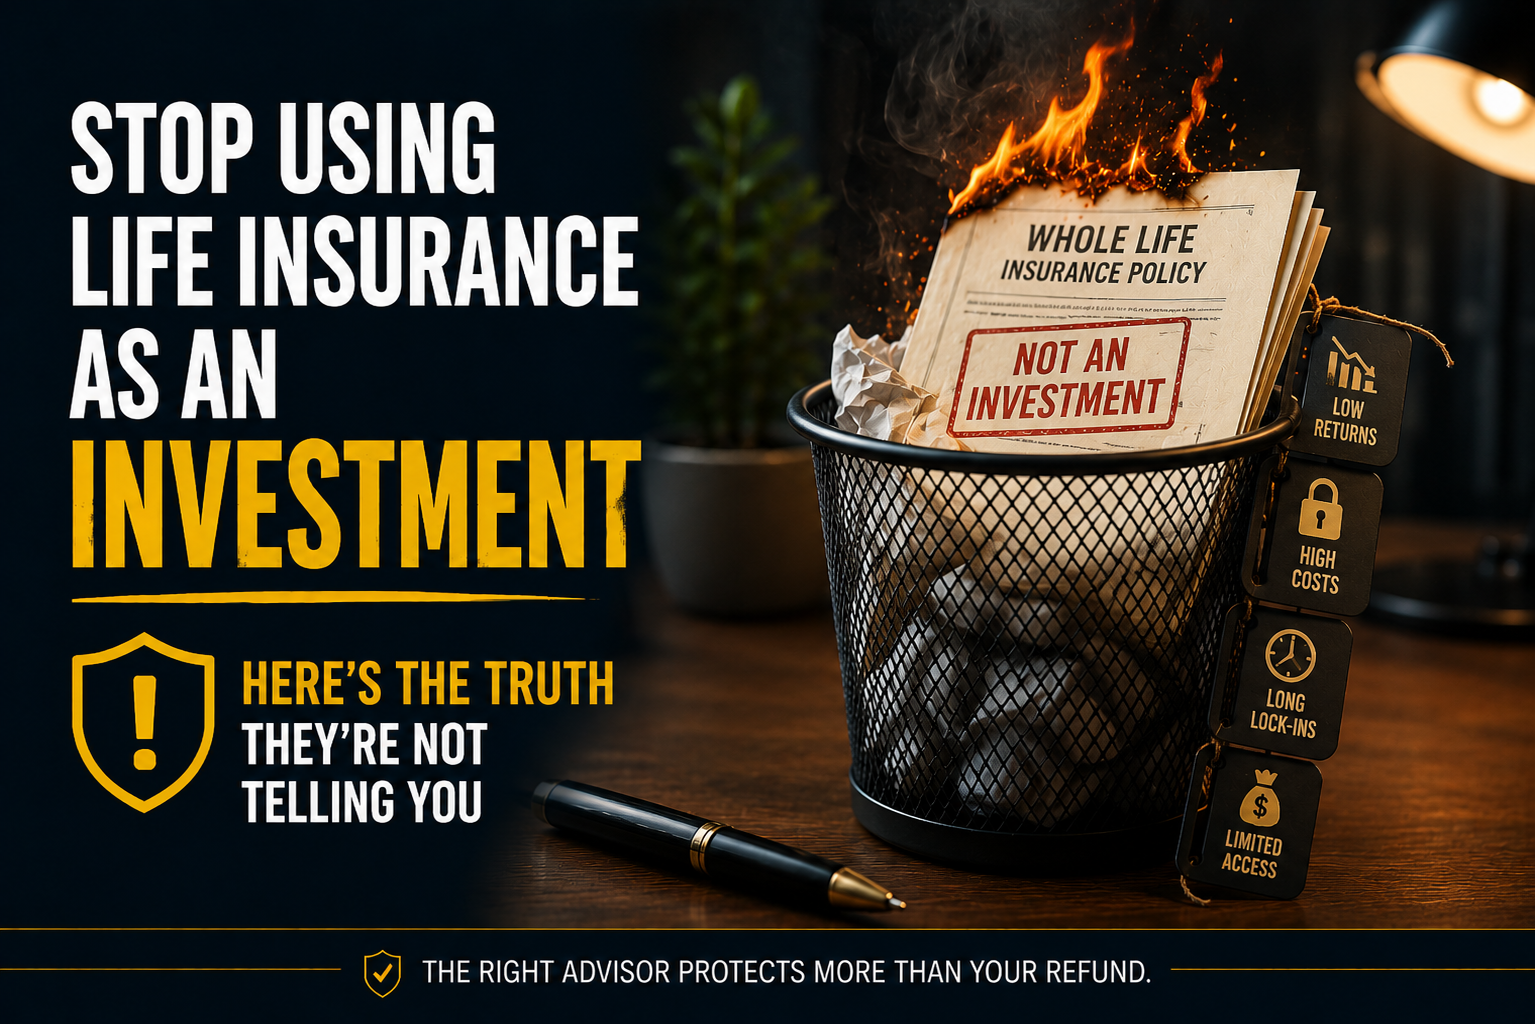
But here's the truth: life insurance was never designed to be an investment vehicle. And when you try to make it one, the only person who wins is the insurance company.
Let's break it all the way down.
What Life Insurance Is Actually Supposed to Do
Before we go any further, let's get clear on the purpose of life insurance.
Life insurance has one job: replace your income if you die so your family doesn't fall apart financially. That's it. Full stop.
It is not a savings account. It is not a retirement plan. It is not a wealth-building tool. It is income protection — and when it stays in that lane, it works beautifully.
The problem starts when insurance companies figured out they could charge you significantly more by bundling your coverage with an investment component. They called it "cash value." They dressed it up with words like "tax-advantaged growth" and "living benefits." And they've been selling it ever since.
Don't fall for it.
What Is Cash Value Life Insurance?
Cash value life insurance — also called whole life, universal life, indexed universal life, or variable universal life — is a permanent life insurance policy that includes an investment account alongside your death benefit.
Here's how it works:
You pay a monthly premium. A portion of that premium covers your life insurance. The rest gets deposited into a cash value account that is supposed to grow over time. Once you've built up enough cash value, you can borrow against it or withdraw from it.
Sounds reasonable on the surface. But let's look at what's actually happening underneath.
The Part They Don't Tell You Up Front
Here's where the real conversation starts, family.
The returns are terrible.
The cash value account in most whole life policies grows at a rate set by the insurance company — typically somewhere between 1% and 4%. Meanwhile, a solid growth stock mutual fund has historically averaged returns of 10–12% over the long term. You are leaving a massive amount of money on the table every single year your money sits in that low-return account instead of working for you in the market.
The fees are real.
Insurance companies don't manage your money for free. There are premium fees, administrative fees, surrender charges, and investment management fees quietly eating away at whatever growth you do accumulate. By the time all the fees are accounted for, your actual return is even lower than advertised.
The cash value doesn't go to your family.
This is the one that stops people cold when they hear it. In most whole life policies, when you die, your family receives the death benefit — but the insurance company keeps the cash value. All those years of "building" that account? The company gets it. Your family gets the face value of the policy, not a dollar more.
Read that again.
You paid into a cash value account for 20, 30, maybe 40 years — and when you pass away, that money doesn't go to your children. It goes back to the insurance company.
That is not generational wealth. That is a generational trap.
The Real Cost of Choosing Whole Life Over Term
Let's talk numbers — not in a complicated way, but in a real way.
A whole life insurance policy for a healthy 35-year-old can easily run three to ten times more per month than a comparable term life policy. The difference in monthly premiums between a whole life policy and a 20-year term life policy for the same coverage amount can be hundreds of dollars every single month.
Now here's what I want you to think about. What if you took that difference — that extra money you would have spent on whole life premiums — and invested it every month into a good growth stock mutual fund inside a Roth IRA?
Over 30 years, at a historical average return, you could be looking at hundreds of thousands of dollars in real, accessible, transferable wealth. Wealth that your family can actually touch. Wealth that doesn't disappear when you die.
That is the power of investing the right way instead of letting an insurance company hold your money hostage.
"But What About the Tax Benefits?"
This is the most common objection I hear, and I want to address it directly.
Yes, the cash value in a whole life policy grows tax-deferred. That sounds attractive. But here's what they don't tell you — you can get tax-advantaged growth in far better places.
A Roth IRA grows completely tax-free. Not tax-deferred — tax-free. You invest after-tax dollars, and when you retire, every dollar you pull out is yours with no tax bill attached. And unlike a whole life policy, you control exactly where your money is invested. You can choose mutual funds with strong long-term track records. You are in the driver's seat.
A 401(k) through your employer — especially if they offer a match — gives you immediate returns that no insurance product can compete with. Free money is always the best investment.
The tax argument for whole life insurance falls apart the moment you compare it to the options already available to you.
Who Is Actually Winning With Whole Life Insurance?
I want you to think critically for a moment.
Why do insurance agents push whole life so hard? Why does it come up in so many financial conversations in our community?
The commissions on whole life insurance policies are significantly higher than the commissions on term life policies. An agent selling you a whole life policy earns far more money than an agent selling you a term policy. That doesn't mean every agent has bad intentions — but it does mean the incentive structure is not designed with your best interest at the center.
When someone is pushing a financial product hard, always ask: who benefits most from this transaction?
The Right Way to Protect Your Family and Build Wealth
Here is the plan. Simple. Actionable. No gimmicks.
Get term life insurance.
A 15 to 20-year term life policy worth 10 to 12 times your annual income is all you need. It protects your family at a price that makes sense, and it does the one job life insurance is supposed to do.
Invest the difference.
Take the money you would have spent on whole life premiums and put it to work. Start with your 401(k) if your employer offers a match. Then open a Roth IRA and invest in growth stock mutual funds with a strong long-term track record.
Stay consistent.
Wealth is not built overnight. It is built through discipline, consistency, and time. The families who win financially are not the ones who found the best product — they are the ones who stayed the course with a simple, proven plan.
Build a real legacy.
Your children's children's children deserve more than a death benefit. They deserve a family that understood money, made wise decisions, and left something real behind. That starts with you making the right call today.
What To Do If You Already Have a Whole Life Policy
If you currently have a whole life policy, do not cancel it tomorrow without talking to a trusted, independent financial advisor first. Depending on how long you've had the policy and your current health situation, there may be factors to consider before making a change.
But do the math. Sit down and honestly compare what you are paying every month versus what you could be building if that money were invested differently. Look at the actual growth rate of your cash value. Ask your agent directly what happens to your cash value when you die.
The answers will tell you everything you need to know.
Conclusion
Family, I need you to hear this clearly.
Life insurance is not an investment. It is protection. And the moment you try to make it do both jobs, you end up with a product that does neither one well — while the insurance company profits from the confusion.
Here is what we covered today:
- Whole life insurance bundles coverage with a cash value account that grows slowly and comes loaded with fees
- When you die, the insurance company keeps your cash value in most policies — your family only gets the death benefit
- The premium difference between whole life and term life, invested wisely over time, can build real generational wealth
- Term life insurance protects your family at a fraction of the cost
- A Roth IRA and 401(k) are far superior vehicles for tax-advantaged wealth building
Here is your next move: If you do not have life insurance yet, start by getting a term life quote today. If you already have whole life, get a second opinion from a fee-only financial advisor who does not earn commissions on what they recommend.
You work too hard for your money to let it sit in a product that was designed to benefit someone else.
Now I want to hear from you — have you ever been sold a whole life policy? What did they tell you? Drop it in the comments. Let's talk about it together.
Keep building,

Anthony O'Neal is a bestselling author, speaker and personal finance educator. He teaches families how to get out of debt and build real wealth on any income through The Escape Plan, his show The Table with AO, and the In the Black app.
more articles
Money Tips
October 15, 2026
When Your Budget Falls Apart Mid-Month, Do This
Money Tips
October 14, 2026
Stop Buying Dad Stuff. Give Him This Instead.
Money Tips
October 14, 2026
Still Living Paycheck to Paycheck? Here's the Budget App Difference Nobody Explains
Money Tips
October 13, 2026
The Real Timeline: What It Actually Takes to Become Debt-Free
Money Tips
October 13, 2026
Your Guide to Debt Payoff Apps: What They Do, What They Don't, and How to Choose One
Money Tips
October 12, 2026
The Quiet Cost of Ignoring a Credit Card Bill
Where this fits
The Escape Plan
Five phases, one plan. Find where you are, then take the next step.
In the Black
A coach in your pocket
Daily money assignments and real accountability, built around the Escape Plan. Know your next step every single day.
$19.00 a month
Get In the Black →Get the plan in your inbox.
Weekly money tips, real stories, and my free Wealth Checklist.
Free. Unsubscribe anytime.